What is the scope and market significance of the Precious Metal Catalysts Market?
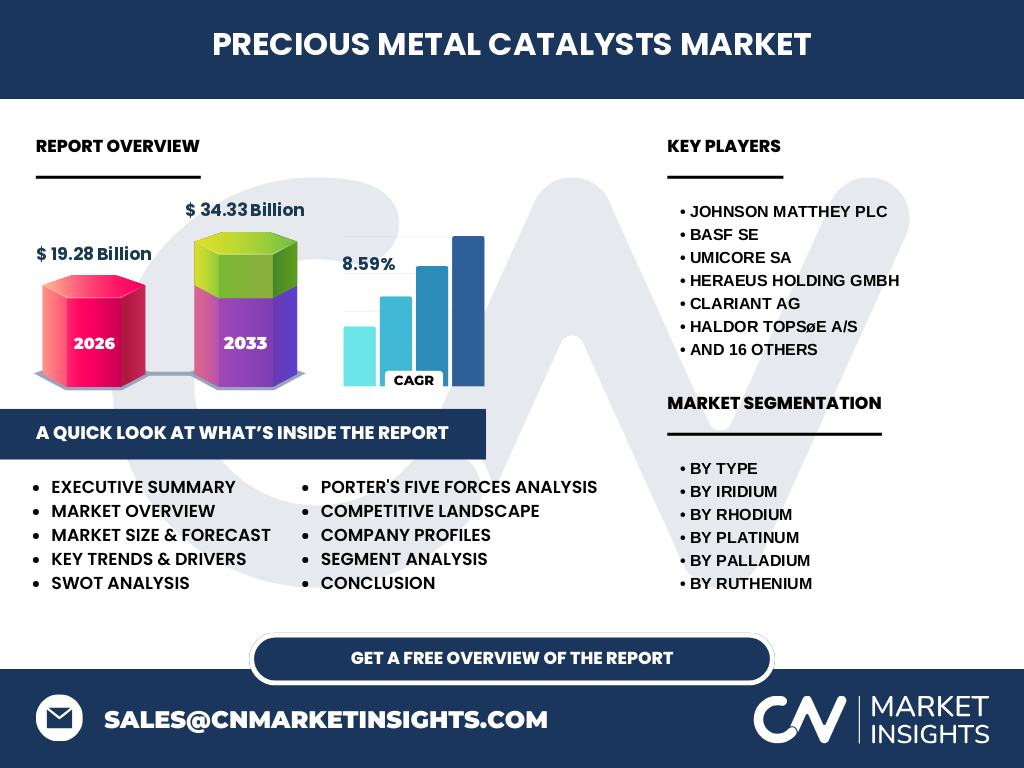
Our analysis indicates that the Precious Metal Catalysts Market size is valued at $19.28 billion in 2026, underscoring its critical role in facilitating complex chemical transformations. This sector encompasses high-value catalysts built from platinum, palladium, rhodium, iridium, ruthenium, and specialized alloys, which are indispensable for driving chemical kinetics in demanding industrial environments.
Key market drivers, restraints, challenges, and opportunities shaping the sector
The market is propelled by stringent environmental regulations enforced by bodies like the EPA and European Union, mandating advanced automotive emission controls. However, extreme price volatility of platinum-group metals (PGMs) acts as a persistent restraint. Opportunities lie in developing recyclable and mixed formulations to mitigate supply chain bottlenecks originating from major mining hubs in South Africa and Russia.
Emerging trends and growth patterns in Precious Metal Catalysts Market industry trends
A defining trend in Precious Metal Catalysts Market industry trends is the rapid pivot toward green hydrogen production, heavily accelerating demand for supported and homogeneous iridium and platinum formulations. Industry leaders are focusing on reducing metal loading without sacrificing catalytic activity, addressing both cost pressures and sustainability mandates across petrochemical and refining applications.
How did the COVID-19 pandemic affect the sector and what is the recovery trajectory?
The pandemic severely disrupted primary PGM mining operations and automotive supply chains, causing temporary contractions in demand across petrochemical and oil refining end-users. Recovery has been robustly steered by post-pandemic industrial stimulus packages and aggressive global decarbonization targets, propelling the sector toward a projected CAGR of 8.59% through the forecast period.
Competitive benchmarking and strategic dynamics among industry leaders
The competitive landscape is consolidated around tier-one chemical and refining technology providers. Market leaders leverage proprietary PGM refining and closed-loop recycling networks to secure raw material supply. Competitors differentiate through customized heterogeneous and homogeneous catalyst formulations optimized for specific reaction types such as asymmetric hydrogenation and carbonylation.
Executive summary of key findings for the Precious Metal Catalysts Market
Our comprehensive research reveals that the Precious Metal Catalysts Market analysis points to an expansion from $19.28 billion in 2026 to $34.33 billion by 2033. Driven by tightening emission norms and clean energy transitions, stakeholders must prioritize PGM recycling capabilities and advanced alloy development to capture high-margin opportunities in automotive and chemical synthesis sectors.
Projected growth trajectory from 2027 to 2033
Based on our econometric models, the market is set to expand rapidly from 2027 through 2033, achieving a stellar CAGR of 8.59% to reach $34.33 billion by the end of the forecast window. This trajectory is underpinned by surging infrastructural investments in green hydrogen and strict global compliance standards in petroleum refining.
Segmentation analysis across types, applications, and reaction mechanisms
The market is comprehensively segmented by type into platinum, palladium, rhodium, iridium, ruthenium, and other variants like mixed or recyclable catalysts. Applications span automotive, refining, petrochemical, and oil and mining sectors. Crucial reaction types include hydrogenation, reductive amination, alkylation, and carbonylation, dictating specific structural requirements like supported versus homogeneous catalyst configurations.
Geographic distribution and regional performance dynamics
Regional performance varies based on local industrial density and environmental legislation. The Asia-Pacific region dominates consumption due to massive refining and automotive manufacturing hubs in China and India, while North America and Europe maintain strong demand centered on stringent emissions standards and early adoption of green hydrogen electrolysis technologies.
In-depth regional review of key operational geographies
In North America, demand is anchored by strict EPA regulations governing petroleum refining and heavy-duty diesel emissions. Meanwhile, Asia-Pacific acts as the primary volume engine, driven by rapid capacity expansions in Chinese petrochemical complexes and expanding Indian pharmaceutical manufacturing requiring advanced hydrogenation and carbonylation catalysts.
Strategic positioning of leading companies in the Precious Metal Catalysts Market
Industry stalwarts such as Johnson Matthey Plc, BASF SE, Umicore SA, and Heraeus Holding GmbH dominate through vertically integrated PGM refining and closed-loop recycling infrastructure. Meanwhile, specialized regional innovators like Sino-Platinum Metals and Tanaka Kikinzoku Kogyo capture niche demands in high-purity electronic and chemical synthesis applications.
Porter's Five Forces assessment of competitive intensity
Bargaining power of suppliers is exceptionally high due to the oligopolistic control of raw PGM mining by entities in South Africa and Russia. Threat of substitutes remains low in critical automotive and high-temperature refining reactions where platinum-group metals exhibit irreplaceable catalytic performance, though R&D into non-noble alternatives poses a long-term watch item.
SWOT analysis of the Precious Metal Catalysts Market
Key strengths include unmatched catalytic efficiency and established recycling networks. Weaknesses center on high exposure to PGM price volatility. Opportunities abound in green hydrogen PEM electrolyzers, while threats include geopolitical supply disruptions and tightening trade tariffs on strategic raw materials.
Value chain structure from primary mining to end-user deployment
The value chain originates with PGM mining and refining in concentrated global regions, transitioning to chemical synthesis houses where active metals are deposited onto supports like alumina or carbon. Fabricated catalysts are then supplied to automotive manufacturers, petroleum refiners, and fine chemical producers, culminating in end-of-life metal recovery and recycling.
Strategic investment insights and high-potential growth pockets
Investors should direct capital toward companies pioneering iridium and platinum catalysts designed for PEM water electrolyzers. Furthermore, firms possessing proprietary PGM recovery and refining technologies offer superior risk-adjusted returns amid ongoing primary raw material supply constraints.
Conclusion and primary strategic takeaways for market stakeholders
The Precious Metal Catalysts Market analysis demonstrates robust fundamentals anchored by an 8.59% CAGR. Success in this capital-intensive sector requires securing resilient PGM supply chains, investing in closed-loop recycling infrastructure, and aligning product portfolios with accelerating global decarbonization initiatives.
Research methodology for baseline estimation and data triangulation
Our baseline estimates are rigorously triangulated by synthesizing official trade registry data from customs authorities, primary stakeholder interviews with C-suite executives at leading catalyst manufacturers, and secondary macroeconomic indicators tracking global automotive production and petrochemical throughput.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market sizing and forecasts from 2026 to 2033, broken down by metal type, application sector, and reaction mechanism. Limitations include unforeseen geopolitical shocks affecting primary PGM extraction and sudden shifts in battery electric vehicle adoption rates impacting autocatalyst demand.
Recent developments, strategic partnerships, and product launches
Recent market activity highlights major players forging joint ventures to secure ethical PGM supply chains and scaling up manufacturing facilities for green hydrogen electrolysis catalysts. Companies are heavily investing in advanced recycling technologies to offset virgin metal mining dependencies and stabilize operating margins.